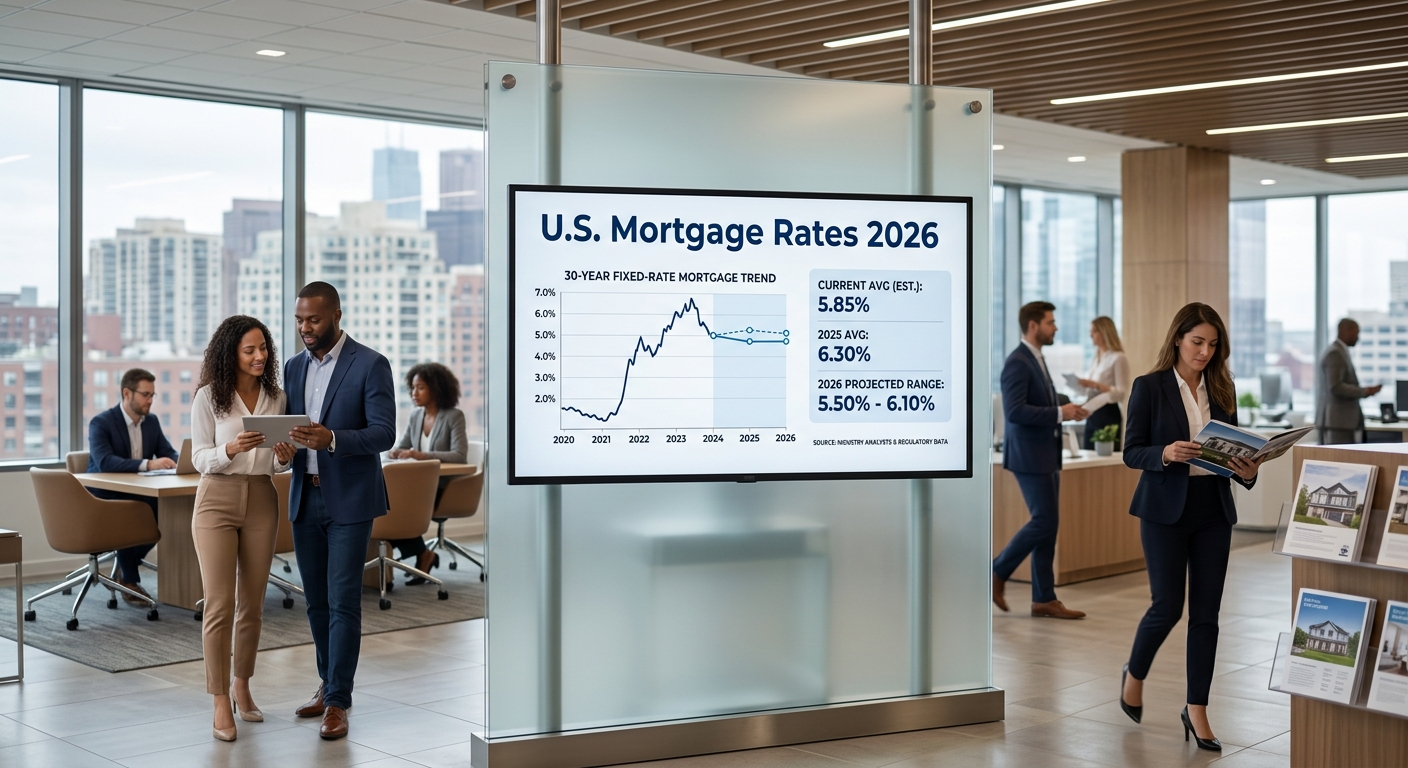
The U.S. housing market in October 2026 is facing renewed affordability concerns as mortgage rates remain elevated, making homeownership more expensive for millions of Americans. With the average 30-year fixed mortgage rate reported at approximately 7.4% on October 15, prospective buyers are confronting higher monthly payments, while homeowners and real estate investors are reassessing their financial plans.
High borrowing costs have become a major challenge for the American property market. Although housing demand varies across cities and states, expensive mortgages can discourage first-time buyers, reduce purchasing power, and slow property transactions.
The central question is whether the housing market is entering a broader slowdown or simply adjusting to a period of higher financing costs. The answer depends on several factors, including mortgage rates, housing supply, household incomes, employment conditions, and local property prices.
For buyers, sellers, investors, and policymakers, understanding these trends is essential to navigating the U.S. real estate market in 2026.
Why U.S. Mortgage Rates Remain a Major Concern
Mortgage interest rates determine how much borrowers pay to finance a home. Even a relatively small increase in rates can significantly affect monthly payments, particularly for buyers purchasing expensive properties.
The average 30-year fixed mortgage rate was reported at approximately 7.4% on October 15, 2026. At this level, borrowers may face substantially higher financing costs than they would at rates closer to 5% or 6%.
Mortgage rates are influenced by several factors, including Treasury bond yields, inflation expectations, financial-market conditions, and investor demand for mortgage-backed securities. They do not move in direct lockstep with the Federal Reserve’s benchmark interest rate.
Consequently, even if the Federal Reserve reduces its policy rate, mortgage borrowing costs may remain elevated if bond yields and inflation expectations stay high.
How High Mortgage Rates Affect Monthly Payments
Consider a buyer financing a $350,000 home with a $70,000 down payment. The resulting mortgage would be $280,000.
At an illustrative fixed interest rate of 7.4% over 30 years, the principal-and-interest payment would be approximately $1,936 per month. At a 6% rate, the payment would fall to approximately $1,679.
That difference of around $257 per month represents more than $3,000 annually, excluding property taxes, homeowners insurance, maintenance, and other housing expenses.
For households already managing higher grocery, energy, healthcare, and transportation costs, this additional expense can make purchasing a home financially difficult.
Is the American Housing Market Losing Momentum?
High mortgage rates can reduce demand, but they do not automatically cause property prices to fall nationwide.
The U.S. housing market is highly regional. Conditions in California, Florida, Texas, New York, and the Midwest can differ considerably because of local employment trends, construction activity, population growth, insurance costs, and available housing inventory.
First-Time Buyers Face the Greatest Affordability Challenges
First-time homebuyers are particularly sensitive to borrowing costs because they generally have less housing equity and may have limited savings for down payments and closing expenses.
Higher mortgage payments can force prospective buyers to consider smaller properties, move farther from employment centers, or postpone purchasing altogether.
Younger households may also struggle to save for a down payment while paying rent. This can create a cycle in which expensive housing delays homeownership and makes it harder to build long-term household wealth.
For many buyers, affordability depends on the combined cost of the mortgage, property taxes, insurance, utilities, and maintenance rather than the advertised home price alone.
Existing Homeowners Are Reluctant to Sell
Another factor affecting the housing market is the so-called mortgage rate lock-in effect.
Homeowners who secured mortgages at substantially lower interest rates may be reluctant to sell and replace their existing loans with more expensive financing. Moving to a different property could increase their monthly payments even if the new home is similarly priced.
This can reduce the number of homes available for sale and limit the number of transactions.
The resulting market can experience weaker sales activity without a corresponding nationwide collapse in property values. In areas with limited supply and strong employment, prices may remain relatively resilient despite high borrowing costs.
Housing Inventory Could Change the Outlook
The balance between available homes and buyer demand is critical to property prices.
If more sellers list their properties while buyers remain cautious, inventory can increase and give purchasers greater negotiating power. Sellers may respond by lowering asking prices, offering closing-cost assistance, or accepting longer marketing periods.
However, if housing supply remains limited, high mortgage rates may suppress transactions without causing substantial price declines.
This is why national housing headlines do not always reflect conditions in an individual city or neighborhood.
What High Mortgage Rates Mean for U.S. Real Estate Investors
Real estate investors are also adjusting to the financing environment. Higher borrowing costs can reduce cash flow, increase the amount of capital needed for acquisitions, and make some projects less attractive.
Rental Property Returns Face Greater Pressure
Investors purchasing rental homes must compare expected rental income against mortgage payments, property taxes, insurance, repairs, vacancy periods, and management fees.
When financing costs rise, a property that previously generated positive monthly cash flow may become less profitable.
Investors may respond by negotiating lower purchase prices, increasing their down payments, focusing on markets with stronger rental demand, or avoiding properties with weak projected returns.
However, expensive homeownership can also support rental demand when households postpone buying. This may benefit some landlords, although higher insurance, maintenance, and financing expenses can offset the advantage.
Commercial Real Estate Faces Its Own Challenges
Commercial property owners and developers are sensitive to borrowing costs because many projects depend on refinancing and long-term debt.
Higher rates can increase refinancing expenses, reduce property valuations, and make new developments harder to finance.
Office buildings, apartment complexes, warehouses, and retail properties have different risk profiles, so the impact varies by location and asset type.
Investors should pay close attention to debt maturities, occupancy rates, lease income, and the availability of refinancing rather than relying solely on expectations of future property-price growth.
Could Mortgage Rates Fall in 2026?
The future direction of mortgage rates depends on inflation, economic growth, bond-market expectations, and Federal Reserve policy.
If inflation moderates and financial markets anticipate lower short-term interest rates, mortgage rates could ease. A sustained decline in Treasury yields may also reduce financing costs for homebuyers.
However, persistent inflation, rising government borrowing needs, or renewed economic uncertainty could keep long-term borrowing costs elevated.
The Federal Reserve does not directly set standard 30-year mortgage rates. Its decisions influence broader financial conditions, but mortgage pricing also reflects long-term interest-rate expectations and mortgage-market risks.
Buyers should therefore avoid assuming that a future Fed rate cut will immediately make mortgages affordable.
Will Lower Rates Bring Buyers Back?
A meaningful decline in mortgage rates could improve purchasing power and encourage some households that delayed buying to return to the market.
It could also encourage existing homeowners to sell, increasing the supply of properties available to buyers.
Nevertheless, lower rates may stimulate demand faster than new housing construction can respond. In markets with limited inventory, renewed demand could support higher prices and reduce some of the affordability benefits.
The overall result would depend on how quickly borrowing costs change and whether housing supply expands alongside demand.
Regional Housing Trends Across the United States
National mortgage rates affect buyers throughout the country, but regional conditions remain essential.
California: Expensive homes and high living costs make affordability a major concern, particularly for buyers in coastal metropolitan areas. Insurance costs and local supply constraints can add further pressure.
Texas: Large metropolitan areas such as Dallas, Houston, and Austin have different construction patterns and housing inventories. Buyers should assess local employment, property taxes, insurance, and new-home supply.
Florida: Population movements, insurance premiums, property taxes, and exposure to severe weather can influence housing costs alongside mortgage rates.
New York: High property prices in parts of the state and additional taxes or maintenance expenses can make monthly ownership costs substantially higher than principal and interest alone.
Midwestern markets: Some cities offer comparatively lower home prices, but affordability still depends on local wages, property taxes, insurance, and employment opportunities.
For homebuyers and investors, local data on inventory, days on market, sales prices, rent levels, and new construction provide a more useful picture than a national average alone.
How the U.S. Housing Market Affects the Wider Economy
Housing is closely connected to consumer spending, employment, banking, construction, and financial markets.
When home sales slow, spending on furniture, appliances, renovations, moving services, and other household goods can also weaken.
Homebuilders may delay projects if buyers cannot afford new properties. This can affect construction employment, building-material suppliers, contractors, and local businesses.
Banks and mortgage lenders may experience lower demand for new loans and refinancing. At the same time, borrowers facing financial pressure can increase credit risks, particularly if unemployment rises or household income declines.
However, a slowdown in property transactions does not necessarily mean the wider economy is heading into recession. Employment, wage growth, consumer spending, and business investment all help determine the broader economic outlook.
What the Mortgage Market Means for International Buyers and Pakistan
The U.S. housing market also matters to international investors and financial institutions because American interest rates influence global borrowing costs and investment decisions.
For Pakistani investors interested in U.S. property, high mortgage rates can increase acquisition costs and make financing more expensive. Currency movements also matter because the value of the Pakistani rupee against the U.S. dollar affects the local-currency cost of dollar-denominated investments.
Pakistani professionals working in the United States may face similar affordability pressures when purchasing homes, especially in high-cost metropolitan areas.
Meanwhile, broader changes in U.S. interest rates can influence global capital flows and currency markets, although the effect on Pakistan depends on domestic economic conditions and international financial developments.
International buyers should evaluate financing eligibility, taxes, legal requirements, insurance, property-management expenses, and currency risk before making a property investment.
What Homebuyers Should Watch Before Purchasing a Property
With mortgage rates elevated, buyers can take several practical steps to evaluate their options.
- Compare multiple lenders: Interest rates, fees, discount points, and closing costs can differ.
- Calculate the complete monthly cost: Include property taxes, insurance, maintenance, and homeowners association fees where applicable.
- Review the local market: Examine comparable sales, available inventory, and how long similar properties remain listed.
- Consider the holding period: Buying can involve substantial transaction costs, making the expected length of ownership important.
- Avoid relying on rate predictions: Choose financing that remains manageable even if mortgage rates do not fall as expected.
- Maintain financial reserves: Unexpected repairs, income changes, or insurance increases can strain a household budget.
Potential buyers should compare the cost of renting with the full cost of owning rather than assuming that purchasing is always the more affordable long-term option.
Frequently Asked Questions
What is the average U.S. mortgage rate in October 2026?
The rate referenced in this article is approximately 7.4% for a 30-year fixed mortgage as reported on October 15, 2026. Actual offers vary by lender, borrower credit profile, down payment, loan type, and other factors.
Are high mortgage rates causing U.S. home prices to fall?
Not necessarily. High rates can reduce demand and sales activity, but limited housing supply and strong local demand can support prices. Conditions vary significantly across states and cities.
Should buyers wait for mortgage rates to decline?
There is no universally correct answer. Buyers should consider affordability, job stability, available inventory, expected ownership duration, and the risk that future rates or prices may move in either direction.
How do Federal Reserve decisions affect mortgage rates?
Federal Reserve policy influences financial conditions and short-term rates, while 30-year mortgage rates also depend on Treasury yields, inflation expectations, and mortgage-market pricing.
How do U.S. mortgage rates affect Pakistan?
They can influence international investment conditions, dollar financing costs, currency markets, and Pakistani residents or investors purchasing property in the United States. The actual impact depends on broader economic developments.
Conclusion
The U.S. housing market faces a difficult combination of high mortgage costs, affordability pressures, and uneven regional conditions in October 2026. A mortgage rate near 7.4% can significantly increase monthly payments and discourage buyers who are already managing elevated living expenses.
Yet the market is not moving uniformly. Limited housing supply may support prices in some areas, while markets with increasing inventory and weaker demand may experience greater pressure.
For homebuyers, the priority is finding a property and financing arrangement that fit their budgets. For investors, careful analysis of rental income, debt costs, and local conditions is increasingly important.
Ultimately, the direction of the American housing market will depend on the interaction between mortgage rates, inflation, employment, housing supply, and household purchasing power.
Editorial Note: According to Bankrate’s mortgage rate data, U.S. mortgage rates vary by loan type and borrower profile. Rates may change with market conditions. Readers should compare lenders before making mortgage decisions.
Source: Bankrate Mortgage Rates
Author: Anam Younas
Follow Daily Press on X for the latest news and updates: @dailypressit.